Since I started working in the wood processing equipment industry over a decade ago at Huaxin Machinery, I‘ve watched the global wood powder market transform from a niche segment into a multi-billion dollar global industry. And honestly? Most operators still don’t fully grasp the scale of opportunity sitting right in front of them.
Let me share what I‘ve learned about the wood powder market size and the wood flour business opportunities emerging right now — backed by the latest data, real applications, and practical insights from someone who works with these machines every day.
What Exactly Is Wood Powder (and Why Does It Matter)?
Before we dive into the numbers, let’s get clear on terminology. Wood powder (often called wood flour or wood dust) refers to finely ground wood particles typically passing through a 0.63 mm mesh sieve, with waste content not exceeding 8% by weight. It‘s produced from sawdust, wood shavings, forestry residues, and other wood waste through specialized wood powder processing equipment.
Unlike wood pellets — which are compressed into cylindrical solid fuel for heating and power generation — wood powder serves a much broader range of industrial applications. The distinction matters because it directly impacts market size estimation and business model selection.

The Numbers That Matter: Wood Powder Market Size in 2026
Let me break down the current market landscape using the most reliable data available. Different research organizations have published varying estimates depending on whether they track wood pellets, wood flour, or the broader wood waste recycling market. Here’s what I consider the most relevant figures:
- Global Wood Waste Recycling Market
In 2024, this market reached US$14.1 billion, and forecasts project growth to US$19.5 billion by 2030, representing a CAGR of 6%. This market covers wood chips, sawdust, and processed wood powder, with downstream applications spanning the construction, furniture, and power generation industries. - Global Wood Pellet Market
Mainstream Estimation: 2024 global sales reached approximately US$66.13 billion, with projections hitting US$90.06 billion by 2031 at a CAGR of 4.6%.
Optimistic Estimation: Partial institutions predict the market size was US$14.64 billion in 2024 and will potentially soar to US$33.96 billion by 2033 at a CAGR of 9.8%.
According to recent industry analysis, the wood pellet market is expanding rapidly driven by global renewable energy policies and the increasing penetration of biomass fuel. - Wood Wool and Wood Flour Market
Global import trade data: The market scale was approximately US$101.4 million in 2025, achieving year-over-year growth compared with US$89.6 million in 2023.
Major wood flour exporting countries and corresponding export value:
Germany: US$38.7 million
Vietnam: US$17.6 million
The United States: US$7.96 million
Core Conclusion for Business Planning
The combined wood powder-related market (covering wood waste recycling, wood pellets, and industrial wood flour) boasts an annual market size well over US$15 billion, maintaining a steady annual growth rate of 5–7%. It creates tangible and profitable development opportunities for wood powder equipment manufacturers and raw material processors.
Where Is the Growth Coming From?
From my conversations with plant operators across Asia, Europe, and North America, three major drivers are fueling global wood powder market demand:
- Renewable Energy Policies — Governments worldwide are pushing hard on decarbonization. The EU‘s revised Renewable Energy Directive sets binding targets of at least 42.5% renewable energy by 2030, with biomass as a key component. Wood pellets and powder as bioenergy feedstocks are direct beneficiaries. The global push for carbon-neutral energy targets and the increasing popularity of biomass power generation are accelerating the adoption of wood-based fuels.
- Fluctuating Fossil Fuel Prices — Natural gas and oil price volatility makes wood-based fuels increasingly attractive, especially for residential heating in Germany, France, Austria, and Poland. The rising demand for renewable heating solutions and the increasing adoption of pellet-fired boilers are fueling wood pellet market expansion.
- Circular Economy Expansion — Companies across construction, automotive, and consumer goods are actively seeking sustainable raw materials. Wood flour as a natural filler for plastics, rubber, and composites directly addresses this demand. The growth of the bioeconomy and the rising focus on green building materials are creating new wood flour business opportunities.
The Applications Driving Wood Flour Business Opportunities
This is where things get interesting. If you’re looking to enter or expand in the wood powder market, understanding where the money is matters more than anything.
Plastics and Wood-Plastic Composites (WPC) — Wood flour serves as a cost-effective filler, lightweight, and eco-friendly filler in plastic manufacturing. It reduces production costs, improves strength and biodegradability, and provides a natural wood-like aesthetic. As green building materials gain traction globally, WPC decking, fencing, and automotive interior components are experiencing rapid adoption. WPC products typically contain 35%–70% wood flour or other plant fibers blended with polymers like polyethylene, polypropylene, or PVC.
Industrial Bio-Fillers — Beyond plastics, wood flour finds applications in rubber manufacturing, adhesives and sealants, paints and coatings, filtration systems, and even 3D printing filaments. Each application demands specific mesh sizes and moisture content — which means opportunity for specialized processing. For thermosetting resins and thermoplastic composites, wood flour is an ideal functional filler. Lignetics Group’s NaturFil™, a wood flour concentrate engineered from responsibly sourced wood residuals, exemplifies how the industry is innovating with pelletized wood flour additives to meet the growing demand for sustainable filler additives in plastic manufacturing.
Biomass Fuel Production — Wood powder is a primary feedstock for pellet production. With Europe holding approximately 57% of the global pellet market (North America 21%, China 8%) and major players like Enviva, Pinnacle, and Lignetics scaling operations, consistent demand for processed wood powder continues to rise. Power generation is the most widely used application for wood pellets, accounting for about 61% of global volume.
Innovative Material Development — This is the frontier I find most exciting. Companies like K‘MAC are developing flexible textiles from Japanese wood flour through co-creation ventures. Research into hydrophobic wood flours, bioplastics, and mycelium-based composites points toward entirely new revenue streams. NaturFil™ from Lignetics is a prime example of how pelletizing wood flour eliminates the mess often associated with bio-fillers and makes the additive easier to process while preventing the formation of flammable dust clouds during processing.

Regional Hotspots for Wood Powder Business in 2026
Based on trade data and market reports, here‘s where the action is:
- Europe
Europe remains the world’s largest consumer market for wood-derived products. The Netherlands (US$13.07 million imports in 2025), Germany (US$9.06 million), and France (US$5.73 million) lead regional import activity.
Driven by aggressive climate policies, soaring regional energy costs and sophisticated existing biomass infrastructure, the European market stays mature and keeps stable growth. Currently, Europe dominates the global wood pellet market, accounting for approximately 57% of global consumption, and this leading position is projected to persist through 2030. - North America
The United States exported approximately US$7.96 million worth of wood flour products in 2022. Meanwhile, domestic market demand is continuously expanding within WPC manufacturing and bioenergy sectors.
Leading regional enterprises including American Wood Fibers and Lignetics are committed to wood waste recycling and utilization, manufacturing premium wood flours and eco-friendly sustainable fillers for diverse industrial scenarios. - Asia-Pacific
The Asia-Pacific region features the most vigorous growth potential across the global market. South Korea records US$10.4 million in related product imports. China acts as both a core producer and end consumer in this industry, while emerging Southeast Asian markets provide accessible entry opportunities for new suppliers.
According to recent industry analysis, China registered an export value of roughly US$817.6 million for wood flour products in 2022.
What This Means for Equipment Decisions
From my years of supplying wood processing machinery, I can tell you that quality wood flour starts with quality equipment. The specific demands of your target market directly determine which machines you need.
For WPC and industrial filler applications: You need consistent particle size control. This requires grinders with built-in classifiers — integrated air classifying systems that separate oversized material and recirculate it for regrinding until the specification is met. For these applications, typical mesh requirements range from 60 to 200 mesh.
For biomass fuel production: Throughput and moisture control become the priorities. Wood powder for pelletizing typically requires finer grinding (under 6 mm) combined with drying capabilities to achieve optimal moisture content below 15%.
For specialty applications like 3D printing or advanced composites: Ultra-fine grinding down to 300 mesh or finer is necessary, along with extremely tight particle size distribution.
The equipment I work with at Huaxin Machinery is designed specifically for these varying requirements — from rugged primary grinders handling logs and slabs to high-precision finishing mills for industrial filler production.

The Cost Equation: Profitability in Wood Powder Processing
Let me be direct about the economics. Wood powder processing can be highly profitable — but only if you fully understand your cost structure.
- Raw Material Costs
Raw material costs vary dramatically across different regions. Sawmill residues (sawdust, shavings, offcuts) serve as the most cost-effective feedstock, which can be sourced from local mills at nearly zero cost. Several processors even receive compensation for collecting and disposing of industrial wood waste.
In contrast, virgin forestry residues designed for high-end premium scenarios require much higher procurement costs. Industry statistics show that wood flour prices fluctuate from US$50 to over US$500 per ton, determined by product quality, particle size and end-use applications. - Processing Costs
Processing expenditures are mainly composed of energy consumption, labor fees and equipment maintenance costs. Notably, the grinding procedure accounts for the largest share of energy expenses within the whole production chain.
Compared with outdated traditional devices, high-efficiency professional grinding systems are able to cut energy consumption by 50% or above. This technological gap plays a decisive role in controlling overall profits and optimizing net profit margins. - Revenue Streams
Revenue potential differs greatly based on targeted downstream markets, with tiered pricing for wood powder products as follows:
Commodity-grade wood flour for fuel pellets: US$80–150 per ton
Specialty wood flour for WPC applications: US$200–400 per ton
Ultra-fine & customized wood powder for advanced industrial use: US$500+ per ton - Core Profit Logic
The most profitable and sustainable businesses in this industry do not compete for low-margin commodity orders by volume. Instead, they match customized processing capabilities with high-value segmented application scenarios to maximize economic benefits.
What’s Coming Next in Wood Powder Markets
Several emerging trends are worth watching closely:
Blended bio-fillers — Combining wood flour with agricultural residues (rice husks, nut shells, straw) creates new material properties and cost advantages. This requires processing equipment capable of handling mixed feedstocks. The increasing use of industrial waste as feedstock is improving manufacturing efficiency across the biomass industry.
Surface-modified wood flours — Chemical treatment during grinding can create hydrophobic or adhesion-enhanced products for specific plastic and coating applications. This adds value well above commodity pricing. CCWood, for instance, has developed a solution for wood flour decay caused by water absorption, lengthening the lifetime of WPC to at least 50 years compared to the current 15–20 years.
Automated quality control — Real-time particle size analysis and automated adjustment of grinding parameters are becoming standard in premium production lines. The investment pays off through reduced waste and consistent product quality. The adoption of automation, IoT monitoring, and AI-powered analytics in pellet production lines is driving operational efficiency and reducing downtime.
Carbon credit opportunities — Wood powder produced from waste streams may qualify for carbon credits in some jurisdictions as a verified emissions reduction activity. This adds a revenue layer that didn’t exist five years ago. Major players are increasingly focusing on sustainable wood sourcing and traceability, with certifications becoming essential for securing long-term supply contracts, especially in Europe and North America.
What’s Coming Next in Wood Powder Markets
After helping dozens of clients launch or expand their wood powder operations, here‘s what I’ve learned works:
Start with your end market, not your equipment. Understand exactly what mesh size, moisture content, and purity your customers need before buying machinery. Overspending on unnecessary capabilities is as bad as under-investing.
Build relationships with raw material sources first. Secure consistent feedstock before scaling production. Interrupted supply chains kill profitability. Many successful operations, like Ecostrat in Ontario, have built their business by sourcing wood waste from pallet manufacturers, sawmills, and cabinet manufacturers across entire provinces.
Invest in testing and quality control from day one. Wood powder markets reward consistency. One bad batch can damage customer relationships permanently.
Consider a phased equipment approach. Start with a versatile primary grinding setup, then add specialized finishing capacity as your customer base and volume grow.
The Bottom Line
The wood powder market size continues expanding across established energy applications and emerging industrial uses. Wood flour business opportunities exist for operators who understand their target markets, invest in appropriate wood powder processing equipment, and maintain consistent product quality.
At Huaxin Machinery, we‘ve spent years developing grinding solutions specifically for wood powder production — from entry-level units to high-capacity automated lines. Whether you’re just exploring the market or ready to scale existing operations, I‘d welcome the chance to help you evaluate your options.
Wood Powder Market: FAQ
Q1: What is the current wood powder market size?
Based on BCC Research data, the global wood waste recycling market — which includes wood powder, wood chips, and sawdust — reached US$14.1 billion in 2024 and is projected to reach US$19.5 billion by 2030 at a CAGR of 6%. The wood pellet segment alone reached approximatelyUS$66.13 billion in 2024.
Q2: What are the main applications driving wood flour demand?
Wood flour serves as a cost-effective filler in plastics and wood-plastic composites (WPC), rubber manufacturing, adhesives, paints and coatings, plus biomass fuel production. Premium applications include 3D printing filaments, filtration systems, and specialty construction materials.
Q3: Which regions have the largest wood powder markets?
Europe leads global consumption, holding approximately 57% of the wood pellet market, followed by North America at 21% and China at 8%. Major importers include the Netherlands, Germany, France, and South Korea.
Q4: What mesh sizes are typically required for different applications?
– WPC manufacturing: 60–200 mesh
– Biomass fuel production: particles under 6 mm
– Advanced industrial applications (3D printing filaments, specialty composites): ultra-fine grinding down to 300 mesh or finer
Q5: What is the growth forecast for the wood powder market?
CAGR projections vary by segment:
– Wood pellets: 4.6–9.8% through 2033
– Wood waste recycling: 6% through 2030
– Industrial wood pellets:8.9–11.3% through 2033 (varies by application)
Q6: What are the most profitable wood flour business segments?
Specialty applications generally offer higher margins than commodity fuel-grade products. Ultra-fine industrial fillers for WPC and plastics, custom-spec products for specific manufacturing processes, and innovative materials like surface-modified wood flours typically command premium pricing.
Q7: Who are the major players in the wood powder market?
Key global participants include Enviva, Pinnacle, Graanul Invest Group, Drax Biomass International, Vyborgskaya Cellulose, and Lignetics. Equipment manufacturers include Huaxin Machinery alongside regional players serving specific markets.
Q8: How does wood powder compare to wood pellets as a business opportunity?
Wood pellets serve primarily as a fuel for heating and power generation. Wood powder has broader applications as an industrial filler and feedstock, creating more diverse revenue streams. Both markets are growing, but wood powder’s industrial applications offer greater margin potential for smaller-scale operators.
Q9: What equipment is needed to start wood powder production?
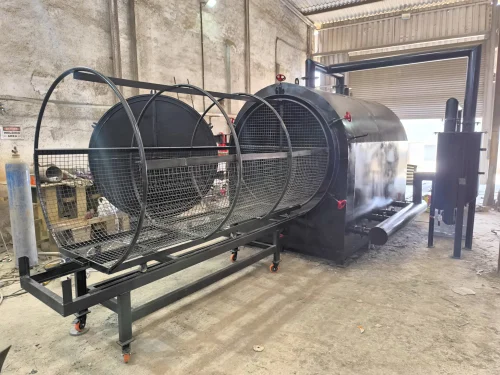
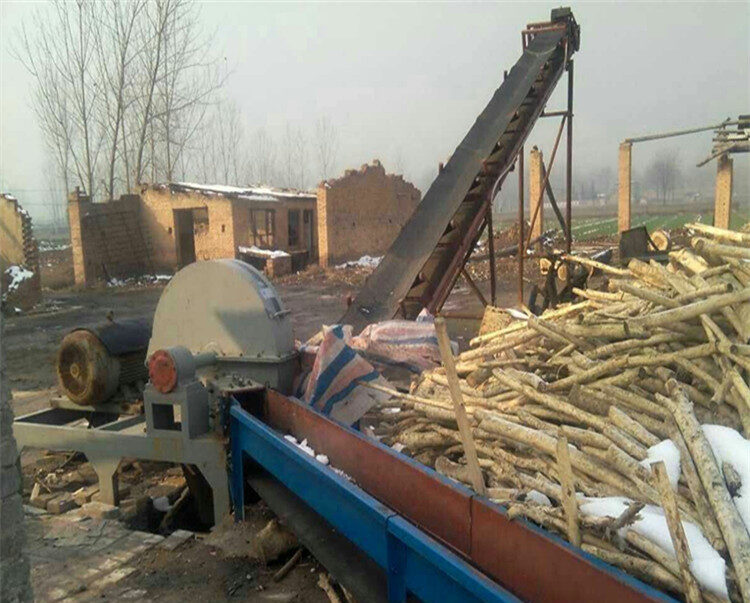
A complete production line typically includes primary grinding (wood chipper/crusher), fine grinding (wood powder mill), classification (air classifier or vibrating screen), drying equipment, and dust collection systems. Equipment specifications depend entirely on target mesh size and production volume.
Q10: What are the key challenges in wood powder processing?
Key operational challenges include high energy consumption (the grinding process is power-intensive), maintaining consistent particle size distribution, stabilizing moisture content, dust control for safety and regulatory compliance, and securing stable raw material supply at cost-competitive prices.
Ready to Scale Your Wood Powder Business?
Whether you‘re exploring entry into the wood powder market or ready to upgrade existing production lines, Huaxin Machinery has the equipment expertise and industry experience to help you succeed.
From single machines to complete production lines — wood chippers, fine powder mills, classifiers, dryers, and dust collection systems — we deliver solutions matched to your target applications and budget.
Contact us today for a FREE consultation and equipment recommendation tailored to your specific wood powder production goals.